Industry insights
Top 135+ Fintech Conferences of 2027: Must-Attend Events for Industry Insights
Fintech and digital banking event lists exist, but they are often fragmented, incomplete, or hard to compare. Relevant conferences are spread across multiple sources with little structure. This curated overview brings them together in one place for 2027.

Industry insights
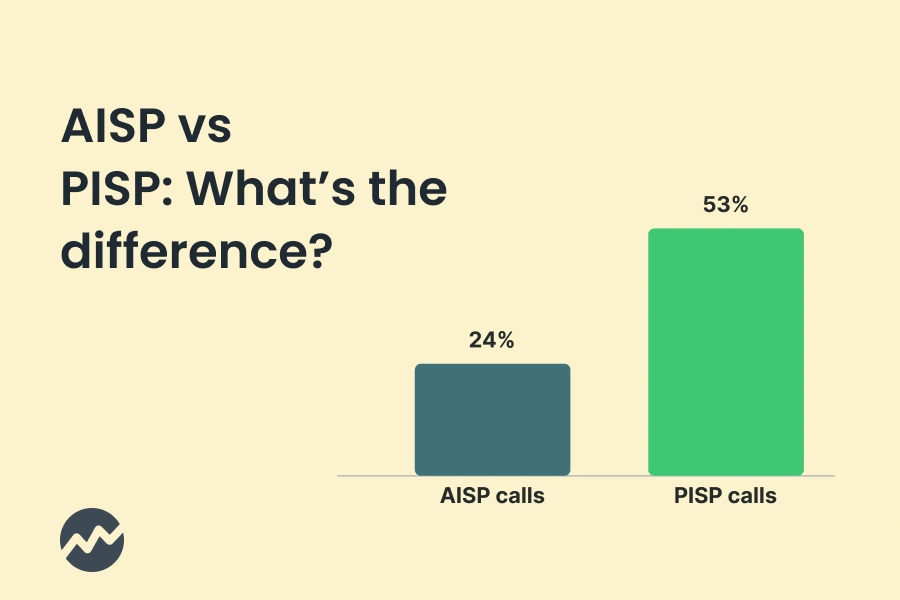
AISP vs PISP: reading payment data vs acting on it
Affordability comes down to one number a lender must evidence: what's left after every expense is paid. That's an account information job start to finish - and it's where the two open banking roles split. An AISP reads the transaction picture that makes affordability calculable; a PISP moves the money once the decision is made, but plays no part in working out whether someone can afford anything. Here's why the two belong in separate boxes, and why adoption is now tilting from the reading role toward the acting one.

Industry insights
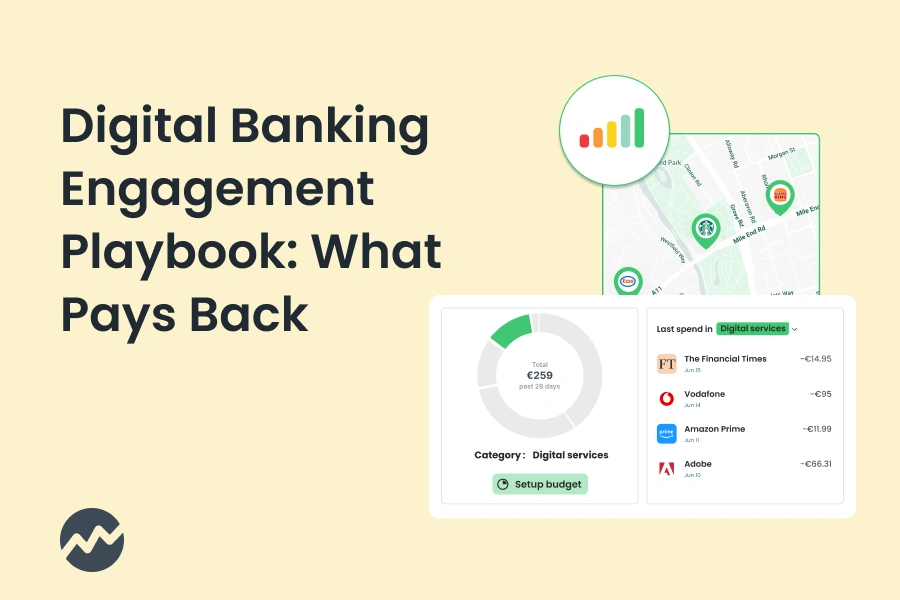
The Digital Banking Engagement Playbook: What Actually Pays Back
An established bank earns several times more per customer than a neobank, and almost none of it comes from the app. The money sits on the balance sheet: the salary paid in, the direct debits cleared against it, the loan on the other side of the ledger. But the app is where that relationship gets defended or quietly lost, feature by feature, as customers decide where their financial routine will live. This playbook cuts through engagement vanity metrics to the features that actually move the number that pays back - and shows why every one of them depends on a bank being able to read what its customers' payments really are.
Industry insights
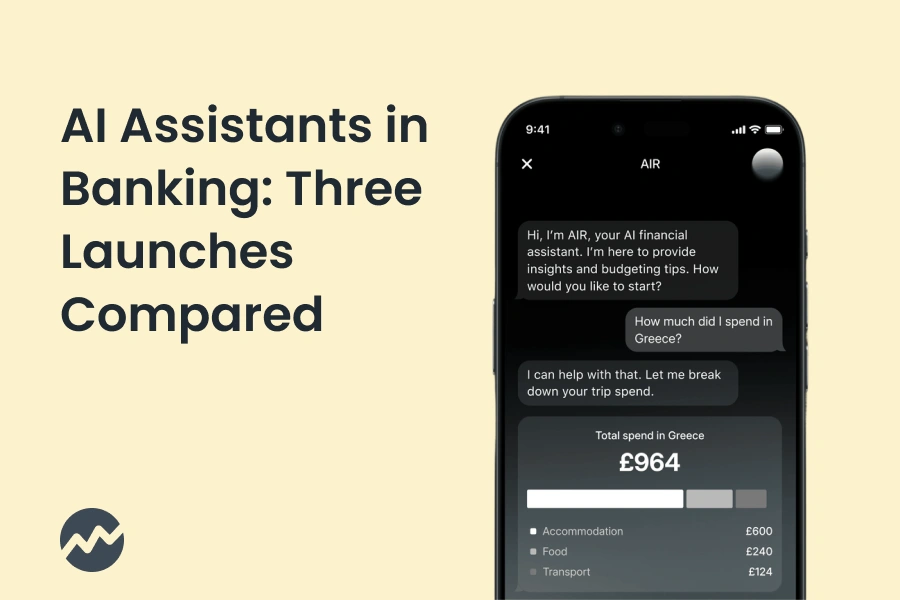
AI Assistants in Banking: bunq, Starling and Revolut
Three banks shipped consumer-facing AI assistants inside twelve months, and to anyone being asked whether their own bank needs one, they look like a single trend. They are not. Measured on what the assistant is allowed to do, what it is allowed to see, and the route each bank took to ship it, bunq Finn, Starling Assistant and Revolut AIR turn out to be three different products - and the differences change what can go wrong with each. Here they are set side by side.
Industry insights
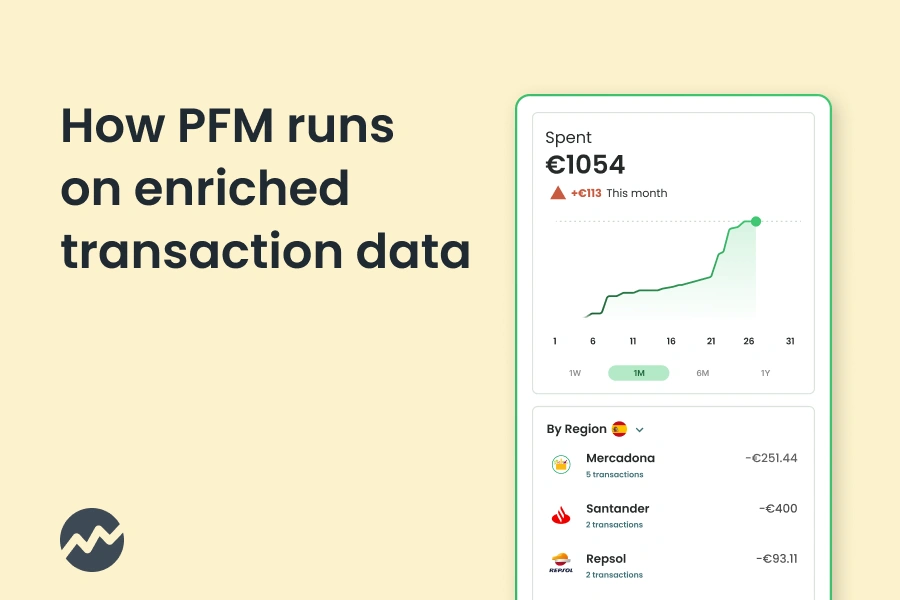
How enrichment expands personal finance management
Every feature in a personal finance app - categories, spending summaries, subscription alerts, carbon insights, even an agent that cancels a forgotten trial - sits on one thing: the quality of the transaction data underneath. Here's how enrichment turns raw payment strings into a PFM customers actually trust, across every payment rail and every market.

Industry insights
What does Generation Z expect from banking?
Gen Z is the heaviest-subscribing generation and fails on those subscriptions at roughly twice the rate of everyone else. But subscriptions are only the start. This piece breaks down four things Gen Z actually expects from a bank - seeing what they pay for, getting answers without digging, having their spending reflected back accurately, and banking with an institution that looks like them - and shows the European evidence behind each. Underneath all four sits the same dependency: a clean, enriched transaction record.

Industry insights
What Are MCC Codes, and Why Aren't They Enough for Transaction Categorisation?
We decided to provide our insights into the power of strictly MCC-based categorisation and its limits. Categorisation is important for credit risk scoring and it is the basis for Personal Finance Management tools. When we analysed our categorisation with MCCs, we saw that only 53% of transactions could be easily and reliably categorised based on their MCC code. Let's look at the most frequent problems we identified that make MCC usage more difficult than it may seem at first glance.


Industry insights
Top 5 Digital Banking Features for Generation Z
Gen Z decides fast whether a banking app is worth keeping open, and the choice comes down to five features: clear transaction history, subscription management, merchant-named notifications, spending insights with an annual recap, and per-transaction carbon tracking. Each one fails in a specific way when the transaction record underneath it is not accurate. This piece walks through those failure modes and the exact data fields that prevent them - and shows why a bank scoping these as five separate builds is really buying the same merchant-identity layer five times over.
Industry insights
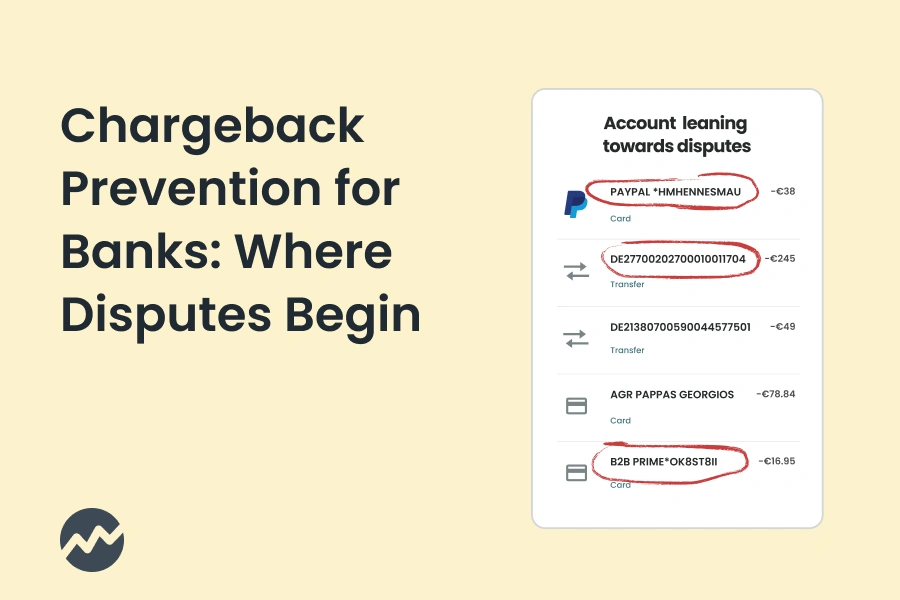
Chargeback Prevention for Banks: Where Disputes Begin
Chargebacks are an important tool providing clients with the ability to dispute transactions and reclaim funds. These happen when a client contacts their bank to reverse a transaction, often because they believe the transaction was unauthorized, fraudulent, or incorrect. Chargebacks themselves also present significant challenges for merchants, banks, and fintech companies, often resulting in substantial financial losses. And the rise of digital banking has only magnified the importance of efficient chargeback management. With many automation tools available, banks need to understand that prevention is often the cheapest and smartest option available, making clear payment history more important than ever.
Industry insights
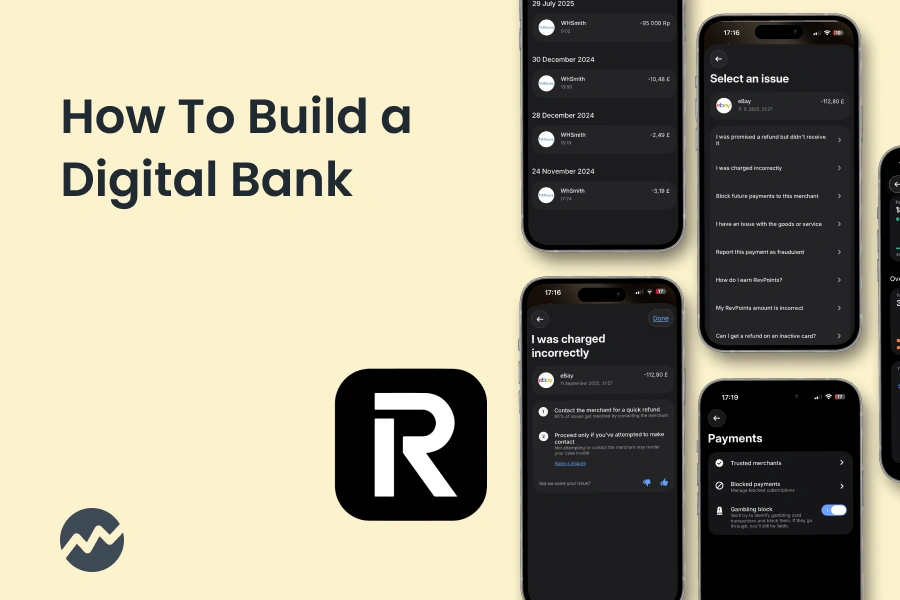
How to Build a Digital Bank
Digital banks serve over 500 million customers worldwide, yet fewer than a quarter turn a profit. This guide covers what it takes to build one - licences, architecture, acquisition cost, and the monetisation levers that lead to sustainable margins - with launch stories from Partners Banka and SwissBorg.
Industry insights
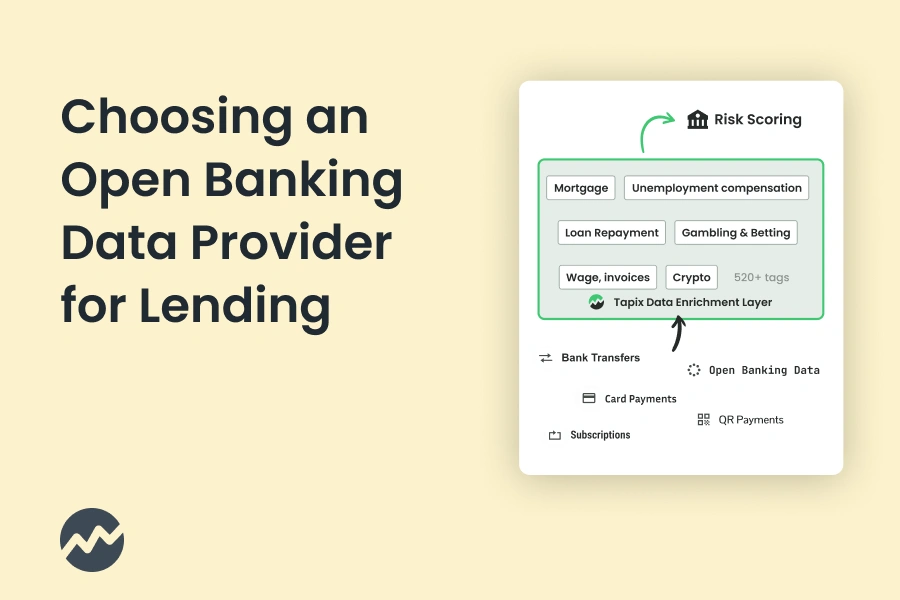
How to choose the best open banking data provider for assessing creditworthiness
CCD2 takes effect on 20 November 2026, and self-declared income won't cut it anymore. But open banking data is far messier than a bank's internal records, so the provider you pick decides how reliable your creditworthiness assessment really is. Here's how to run a proof of concept on your own customers and judge vendors on coverage, accuracy, and classification depth.
Industry insights
鈥岰CD2: Which EU Countries Are Most Prepared for the New Consumer Credit Directive
CCD2 was meant to be transposed across the EU by November 2025, yet many member states still don't have final legislation. The frontrunners are the Nordics and the Netherlands - and each is rewriting creditworthiness assessment its own way. Here's how the Netherlands, Denmark, Sweden and Finland are tightening the rules, and why no credit register alone is enough to comply.
Industry insights
The European Subscription Economy Runs Through Transaction Data. Most Banks Can't Read It
Across Europe, many merchants sell distinct and varied subscription products. That is how the subscription economy appears in bank transaction data: dense, fragmented, and structurally difficult to read. The brand-name surface looks tidy, with Netflix, Spotify and Apple at the front. Underneath, every merchant runs roughly six pricing variations, on average, across different amounts, billing cycles, currencies and payment paths.
Industry insights
Visa and Mastercard Transaction Data Mandates: What European Issuers Need to Meet
Mastercard AN4569 has been in force since 2023, and Visa's enhanced merchant data mandate follows in January 2027. The two requirements overlap more than they differ - and one enrichment layer, built to the right standard, covers both. Here's what European issuers need to meet, where the mandates align, and how to turn compliance into infrastructure.
Industry insights
Sentient Design in Banking: What Needs to Be True Before It Can Work
Banks hold the richest behavioural data of any industry - every purchase, every transfer, every recurring obligation. And almost nothing they build with it feels personal. Sentient design is the model that would change that: interfaces that observe the user, infer what they need, and act before being asked. The model is real, the early examples exist, and bank product teams are starting to ask how to implement it. But every sentient moment depends on something most banks still don't have under control: clean, enriched transaction data that the AI can actually read. But first, you have to start with small steps. So we sat down with Ergomania's design strategist to learn how.
Industry insights
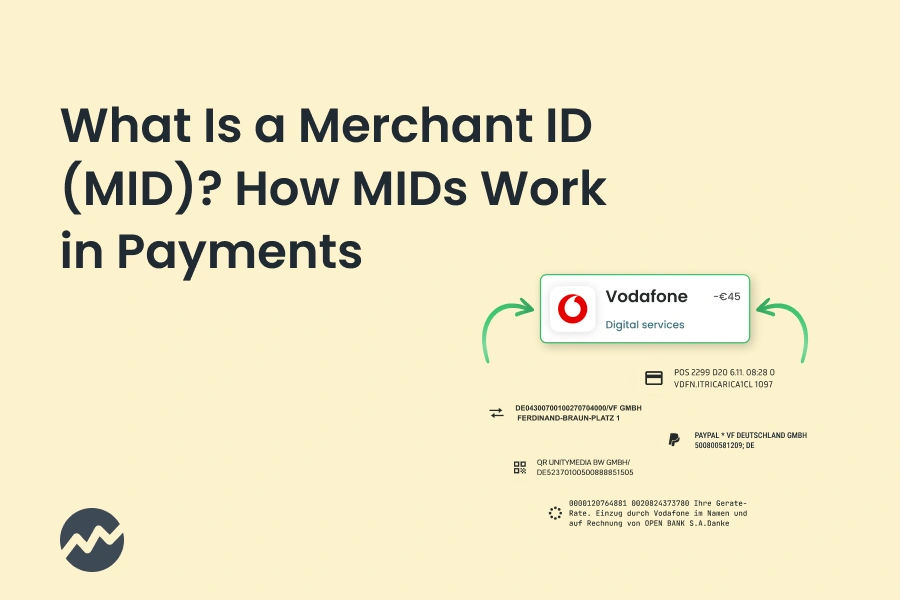
What Is a Merchant ID in Payments? How MIDs Work and Why They Matter for Transaction Data
When a card transaction lands in a bank's core system, it carries a handful of identifiers that determine whether the bank can actually tell its customer where they spent their money. The merchant ID (or MID) is one of the most important of these, and one of the most misunderstood. It is the primary key acquiring banks use to track merchants, and it is one of the main reasons the same real-world business can appear as dozens of unrelated entities in a bank's transaction data.
Industry insights
ISO 8583 vs ISO 20022: What the Messaging Standards Shift Means for Transaction Data
Wholesale and account-to-account payments have largely completed the move and instead of it being ISO 8583 vs ISO 20022, it鈥檚 more of an evolution. Card payments have not - there is no scheme-wide mandate, no fixed timeline, and the European Cards Stakeholders Group has explicitly recommended a market-driven approach. For banks and fintechs, this split reality matters: ISO 20022 is reshaping what transaction data fields are available, how rich that data is, and what you can build on top of it - but on the card rails most issuers depend on, ISO 8583 will remain the operational standard for years.
Industry insights
How AISPs Are Rewiring Financial Connectivity
When PSD2 came into effect in 2018, Account Information Service Providers got a formal identity. Banks had to open their APIs to licensed third parties, and consumers gained the legal right to let those third parties access their payment account data. Seven years later, hundreds of AISPs are registered across Europe, and the model has spread to the UK, Brazil, Australia, and parts of the Middle East.